Independent journal on economy and transport policy
00:31 GMT+2
This page has been automatically translated by Original news
PORTS
Boarding tax in Genoa, the TAR agrees with the Municipality
The appeal of shipowners and shipping agents was rejected
Genova
September 29, 2026
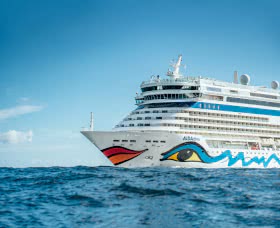
The Regional Administrative Court for Liguria has judged
the levy of three euros per passenger on cruises and
ferries being considered an autonomous tax and not a right
therefore not covered by the European Ports Regulation. The
Second Section of the Regional Administrative Court rejected the appeal by which
Shipowners, Assaagents, Large Fast Ships, Moby, Maritime Stations
and a private citizen, Giulio Uras, asked to cancel
the municipal surcharge on port embarkation fees established by the
Municipality of Genoa.
The levy stems from the agreement between the State and the Municipality signed on 22
November 2022, the so-called "pact for Genoa". The
city - as the sentence of the TAR recalls - was
over-indebted, with a per capita debt of more than 1,000 euros per
inhabitant, even if not in deficit, and had adhered to the procedure
extraordinary rebalancing provided for by Law no. 234/2021 and by the
Decree-Law no. 50/2022. In return, the entity benefits from a
multi-year state contribution. The agreement provided for two measures: a
increase in the municipal Irpef surcharge, with rates between 1% and
1.2% depending on the bracket, and the establishment of an additional
on port boarding fees equal to three euros per person. The
expected revenue was 24.9 million euros per year, of which 19.2 million
million from personal income tax and 5.7 million from the port tax. The Municipality has
raised the personal income tax as of 2022, but the boarding tax has been
introduced only on 16 December 2025 with Resolution no. 72, three years
after the agreement. In the same month, the institution brought all the
Irpef rates at 1.2%, despite the fact that the Ministry of the Interior had
The proposal to reshape the pact in this sense was rejected.
The applicants challenged the resolutions, the agreement and the note with which
the Ministry accused the Municipality of the failure to fulfil its obligations for failure to
establishment of the tax. The Port System Authority of the
Western Ligurian Sea was constituted supporting the reasons
of the applicants. The State administrations and the Municipality have
raised objections of inadmissibility, which the TAR did not
examined, because the appeal was considered
unfounded on the merits.
The shipowners argued that there can be a surcharge
only if there is a main tribute to attach it to, and that
in the port of Genoa there are none on passengers. For the TAR,
however, the term "additional" used by the law is
improper: the legislator has created a derived own tax,
reserved for municipalities with a large deficit or debt. Subordinate it
to the choices of other authorities, taken for different purposes - for
judges - would be illogical, and the tax nature is
confirmed by the three requirements indicated by the case law:
definitive asset reduction, absence of relationship with a
intended to cover public expenses.
Furthermore, the TAR did not find any conflict with the
European Ports Regulation. EU Regulation 2017/352 - recalls
The judgment - regulates the rights that ship operators and
owners of goods pay to use the infrastructure and
port services. The Genoese tax, on the other hand, affects passengers,
who are users of the transport service and not of the port, and it is not
connected to port services. The TAR recalls a recent ruling
of the Council of State on the additional port of Salerno and
considers the complaints on competition to be general, because
Lack of evidence of negative effects on competitiveness
of the airport.
The applicants also argued that the personal income tax
had already exceeded the revenue target on its own and that the
tax was therefore superfluous. The judges of the TAR replied with
three arguments. First, the law requires the application of the two measures
together, as the conjunction "and" indicates. Second,
the objective of the timetable has an indicative value, and the Municipality can
propose a remodulation every year. Third, the higher collection
of personal income tax (13.1 million in 2022, 25.9 in 2023, 36.8 in 2024)
depends only on the rates: part derives from the growth of the
Tax base, estimated at 7.44%, 14.86% and 24.87%. Adjusted,
The effect of the rate increase is 7.7, 15.1 and 18.6
million, still below the 19.2 expected. The increase in
is not decisive: after the growth of 2023 there is
was a decline in 2024 for cruises, with data substantially
confirmed in 2025.
The sentence then recalls that the Municipality justified the measure with
the obligation to comply with the agreement and with the need to
compensate for the inconvenience of port tourist traffic on roads,
transport and urban hygiene. The Regional Administrative Court considers this purpose
implicit in the law, recalling a ruling of the Council of
State on Naples airport, and observes that there was no obligation to
consult the Port Authority and the companies, because
The resolution is a regulatory act, and in any case the subjects
interested parties participated in the meeting of the committees
of 10 December 2025. In that session - reads the
- it was observed that the three euros are equivalent to the
maximum at the price of an aperitif.
For the TAR, the issues
of constitutionality are manifestly unfounded. The judges
exclude that the tax violates territoriality: the port
also falls within the municipal territory, and the Municipality is a multi-purpose entity
general purposes that may, for example, apply the IMU to the areas
concessions. They also exclude the violation of the
reservation of the law, because the law establishes a prerequisite, subjects
liabilities and maximum amount, while the Municipality is responsible for the regulation of
detail, and also exclude the violation of the capacity
contribution: the cruise expresses a spending capacity and -
According to the ruling - even the ferry ticket does so, with
references to the tourist tax and the landing fee.
Finally, according to the TAR, exemptions from the tax do not
are discriminatory. Residents of Genoa,
residents of the destination islands and the security forces,
firefighters and civil protection personnel on duty.
For the Regional Administrative Court, the situations are objectively different, as the
residents do not produce the inconveniences that the tax is intended to compensate, and
are already burdened by the increase in personal income tax; those who return home in
Isola does not travel like those who go on vacation. The European judgments cited
by the plaintiffs then concerned different cases, such as the Sardinian tax
on luxury and Greek port duties.
- Via Raffaele Paolucci 17r/19r - 16129 Genoa - ITALY
phone: +39.010.2462122, fax: +39.010.2516768, e-mail
VAT number: 03532950106
Press Reg.: nr 33/96 Genoa Court
Editor in chief: Bruno Bellio No part may be reproduced without the express permission of the publisher


 The Regional Administrative Court for Liguria has judged
the levy of three euros per passenger on cruises and
ferries being considered an autonomous tax and not a right
therefore not covered by the European Ports Regulation. The
Second Section of the Regional Administrative Court rejected the appeal by which
Shipowners, Assaagents, Large Fast Ships, Moby, Maritime Stations
and a private citizen, Giulio Uras, asked to cancel
the municipal surcharge on port embarkation fees established by the
Municipality of Genoa.







 - Via Raffaele Paolucci 17r/19r - 16129 Genoa - ITALY


