testata inforMARE Prima Pagina
Cerca
11 novembre 2026 - Anno XXX
Quotidiano indipendente di economia e politica dei trasporti
14:35 GMT+1
LinkedInXFacebook
FORUM dello Shipping
e della Logistica

April 2000


DEVELOPING COUNTRIES' MERCHANDISE EXPORTS IN 1999 EXPANDED BY 8.5% -
ABOUT TWICE AS FAST AS THE GLOBAL AVERAGE

Developing countries' merchandise exports in 1999 expanded by 8.5 per cent or about two times faster than the global average. Throughout the 1990s, developing countries' exports rose faster than world trade, with the exception of 1998. In 1999, the share of developing countries was 27.5 per cent for merchandise exports and 23 per cent for commercial services exports, both being more than 4 percentage points higher than in 1990.

Among the least-developed countries, merchandise export growth differed sharply again in 1999. Exporters of manufactured goods like Bangladesh, Cambodia and Haiti expanded their exports faster than world trade. Oil exporters, such as Angola and Yemen, benefitted from the oil price hike and increased their exports by more than one third. While, non-fuel commodity exporters, faced with declining commodity prices, tended to record lower export values.

Global commercial services trade accelerated only slightly in 1999, as the recovery in Asia and higher growth in North America were partly offset by lower growth in Western Europe and an import contraction in Latin America and the transition economies.

These are among the findings of the WTO's preliminary report on trade developments in 1999 and the outlook for this year (full report is attached). Other highlights include the following:

  • Global output and trade strengthened considerably in the second half of 1999, thereby improving the prospects for higher growth in the current year. The recovery in Asia and continued high demand growth in North America contributed most to global trade expansion last year.

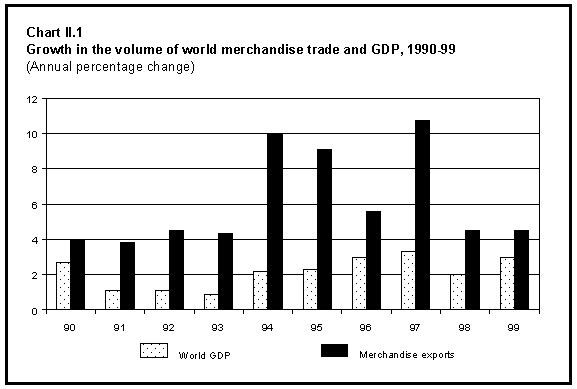
  • World commodity output in 1999 increased by 1.5 per cent, the same as in 1998. A fall in mining sector output (in particular oil) contrasted with stronger growth in the manufacturing sector (e.g. electronic goods and automobiles). The global output of services industries exceeded commodity output growth. World GDP growth increased from 2 in 1998 to 3 per cent in 1999.

  • Trade benefitted from the stronger economic activity. Although for the year as a whole merchandise trade expanded in volume terms at the same rate as in 1998 (4.5 per cent), the pace of the expansion in the fourth quarter exceeded the average rate of 6.5 per cent recorded in the nineties.

  • International capital markets remained buoyant. Global FDI flows surged to a new record level of 800 billion dollars, driven by an exceptionally large value of cross border mergers and acquisitions. The sharp rise in global capital flows was largely concentrated among developed countries. Private net capital flows to emerging markets are estimated to have stagnated in 1999 at about 150 billion dollars.

  • Nominal and real effective exchange rates recorded major variations, leaving their mark on trade flows. While the euro and most European currencies weakened vis-à-vis the US dollar, many East Asian currencies, in particular the Japanese yen, the Korean won and the Thai baht, appreciated markedly.

  • Average prices of internationally traded goods declined slightly. The weakness of the Euro contributed largely to the fall in Western Europe's dollar export prices and a decrease in the prices of manufactured goods. Non-fuel commodity prices continued to weaken further, thus affecting the earnings of many raw material exporters. Oil prices, which had fallen sharply in 1998, recovered strongly in 1999 due to a cutback in oil output and an increase in global demand.

  • World merchandise trade value increased by 3.5 per cent in 1999, faster than commercial services trade. Nevertheless for the 1990-99 period as a whole, commercial services trade still expanded slightly faster than merchandise trade.

  • Thanks to oil price developments, the highest export value growth of all regions in 1999 was recorded in the Middle East and Africa. However, this strong expansion last year did not fully offset the declines recorded in 1998.

  • Merchandise imports grew at double-digit rates in North America and Asia, stagnated in Western Europe and Africa and decreased by about 10 per cent in the transition economies and in Latin America (excluding Mexico).

  • Merchandise export growth among the LDCs differed sharply again in 1999. Oil exporters such as Angola and Yemen benefitted from the oil price hike and increased their exports by more than one-third. Exporters of manufactured goods like Bangladesh, Cambodia, Haiti and Myanmar expanded their exports faster than world trade. Non-fuel commodity exporters faced with declining commodity prices tended to record lower export values.

  • Developing countries' merchandise exports expanded by 8.5 per cent or about two times faster than the global average. Throughout the 1990s developing countries' exports rose faster than world trade, with the exception of 1998. In 1999, the share of developing countries was 27.5 per cent for merchandise exports and 23 per cent for commercial services exports, both being more than 4 percentage points higher than in 1990.

  • Commercial services trade accelerated only slightly in 1999, as the recovery in Asia and higher growth in North America were partly offset by lower growth in Western Europe, and an import contraction in Latin America and the transition economies.


WORLD TRADE DEVELOPMENTS

Main Features

A strengthening of world economic output in 1999 reversed the slowdown of world trade in the first half of 1999 and led to a dynamic expansion of trade in the second half. For the year as a whole, the real growth of world trade remained unchanged from the preceding year and was below the average trade expansion recorded throughout the 1990s. Although trade growth continued to exceed both the growth in world commodity output and world GDP, the excess margin between the growth rates remained smaller in 1999 than those observed during the 1990-1997 period.


Demand in the United States and the Asian recovery were the motors of the global trade expansion in 1999. The outstanding strength of United States investment and private consumption benefitted not only the NAFTA region, but also sustained the recovery in Asia and to a lesser extent output in Western Europe. A major factor behind the excellent performance of the United States economy and the unprecedented length of the current expansion has been the high level of investment in information technology, the backbone of the "new economy". Excitement about the growth potential of the new economy has attracted large capital inflows and contributed to an extraordinary boom in the creation and valuation of high-tech companies. While the high rate of investment has increased production capacity and stimulated productivity growth of the United States economy, the question arises for how long high output and demand growth can be sustained without leading to inflationary pressures. A further risk to the strong economic expansion in the United States could arise from the widening of the current account deficit, which points to the increasing role of foreign savings in sustaining United States demand growth. An erosion of investor confidence in the outlook for the United States economy could lead to lower capital inflows and trigger a correction in the dollar rate and the stock markets.

The recovery in Asia was stronger than expected and led to double-digit real import growth in 1999. GDP growth was uneven among the economies in the region, ranging from 11 per cent in the case of the Republic of Korea to stagnation in the case of Indonesia. In many countries economic growth was sustained by fiscal stimulus, replenishment of inventories and a rebound in the global demand for electronic goods.


The information technology sector and the automobile industry both recorded strong global output growth. Within the information technology sector, the unit sales of personal computers rose by 22 per cent to 114 million units, and the dollar value of global sales of semi-conductors expanded by 18 per cent, to a new record level of 160 billion dollars. One of the most dynamic branches of the global information technology industry in 1999 was mobile phones. It is estimated that world-wide sales of cellular mobile phones reached 283 million units, an increase of two-thirds over 1998 sales. New registrations of passenger cars are estimated to have expanded by 5.5 per cent, lifting the production of passenger cars to a new all time high of 48.6 million units in 1999. Although trade data by product group are still incomplete, there is no doubt that exports of automotive products and of office and telecom equipment have expanded significantly faster than the global average.

Developments in world financial markets continued to influence global trade developments through shifts in the direction of international capital flows and their impact on exchange rate changes. Global FDI flows have surged by about 25 per cent, to some 800 billion dollars. FDI inflows in Asia stagnated or rose only marginally, while the United States recorded net FDI inflows of 130 billion dollars. The main factor behind the increase in global FDI flows was the exceptional wave of cross-border mergers and acquisitions.

While the United States attracted an unprecedented level of capital inflows, which financed its widening current account deficit, net private capital flows to the major emerging markets are estimated to have stagnated at 150 billion dollars in 1999.

The increase in the United States current account deficit caused by increased imports can be seen as a positive cyclical element in the world economy as it allows output and employment to be sustained in foreign export industries facing excess capacity. At the same time, the deficit eases inflationary pressures in the United States where labour and productive capital are increasingly scarce. However, what is beneficial in a certain cyclical situation might be difficult to sustain in the medium term.

In particular, a large current account surplus of the developing countries vis-à-vis the United States (or any other high income country) is hardly a desirable feature over a longer period. Why is this so when most governments seem to favour a current account surplus over a deficit? A current account surplus implies that net capital (= savings) from the developing countries flows to other countries where it supports investment and/or consumption. A more desirable situation for the developing countries is a current account deficit (and a rising trade volume), and a concurrent inflow of capital that is used to enlarge (profitable) production capacity. If the capital inflow is used primarily for consumption, increased debt and debt servicing costs are unlikely to be sustainable.

The present large net capital inflows into the United States reflect, on the one hand, that foreign investors expect investment returns to be higher in the United States than elsewhere, and on the other, that United States consumers are spending an historically high share of current income (encouraged by its increased financial wealth), while United States companies maintain a high level of capital spending. A reversal in foreign investors' appreciation of future earnings in the United States or a cutback in United States consumption or investment growth could rapidly change the size of the United States current account deficit, which in 1999 was equivalent to 3.7 per cent of GDP - a historic record level.

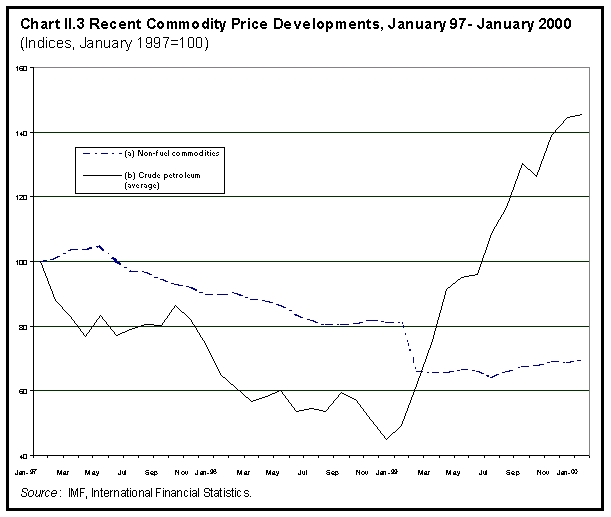
Prices of internationally traded goods decreased slightly as the increase in oil prices was offset by a further decrease in the prices of non-fuel commodities and manufactured goods. Among the non-fuel commodities, prices of food and beverages decreased by more than 15 per cent while those of agricultural materials and metals remained roughly unchanged, although they started to strengthen in the second half of 1999. Despite this partial price recovery, the annual average prices of non-fuel commodities fell to a ten year low. The decrease in the dollar price of manufactured goods can be attributed to the fall in prices of office and telecom equipment as well as the strength of the United States dollar vis-à-vis the euro and the near absence of inflation in the goods sector of all major economies.

Given that oil prices tripled from 10 dollars per barrel in February 1999 to 30 dollars in the first quarter of 2000, concerns about a resurgence of consumer prices are understandable. However, the marked reduction in the oil intensity of output in the industrial countries - by about 40 per cent since the first oil price hike more than 25 years ago - has reduced this risk considerably. The increased role of natural gas in world fuels trade has also contributed to moderate the increase in import prices of fuels. While the impact of the rebounding oil prices have been small on consumer prices in 1999, the impact was dramatic on the export revenues of the oil exporters. The Middle East recorded export growth in excess of 20 per cent in 1999, but this did not fully offset a corresponding decline in 1998.


WORLD TRADE IN 1999

1. Global trade and output developments

While the negative impact of the financial crisis in Asia and Latin America on output and trade flows were initially underestimated, the more sober projections for 1999 turned out to be too pessimistic. Output of developing countries in Asia rebounded by 6 per cent, Russian GDP recovered by 3 per cent and Brazil's economy achieved positive growth for the full year of 1999. The United States economy again provided a major stimulus to world trade last year as domestic demand grew by 5.5 per cent. By contrast, the Japanese economy stagnated and Western Europe's GDP growth decelerated to 2 per cent.

On a sectoral basis, preliminary data suggest that mining output decreased as crude oil production was cut back by 1.5 per cent and agricultural output rose for the second year in a row by only about 1 per cent. Manufacturing output recovered and expanded by about 2.5 per cent. The highly divergent growth rates of regional demand and sectoral output left their mark on global trade flows, which also differed strongly by region and sector.

The value of world merchandise trade rose by 3.5 per cent in 1999 and amounted to 5.45 trillion dollars. Average trade prices decreased for the third year in a row, although the decrease in 1999 was much smaller than in preceding years.

Trade in commercial services rose by 1.5 per cent in 1999 and thereby less rapidly than merchandise trade. Price data for United States commercial services point to a moderate increase in prices for internationally traded services. This implies that the expansion of exports of commercial services has probably also lagged behind merchandise export growth in volume terms.

World exports of merchandise and commercial services, 1997-99
 ValueAnnual change
 1999199719981999
 
Merchandise54603.5-1.53.5
 
Commercial services13404.00.01.5


2. Merchandise trade

A detailed review of world merchandise trade by product group in 1999 is not yet feasible at the time of writing this report. However, partial information indicates that rebounding oil prices have led to an increase of world fuels exports in excess of 20 per cent. Above average growth was also recorded for office and telecom equipment and automotive products. Primary products, other than fuels, on average experienced price declines in 1999. Taking into account moderate demand growth, the global value of non-fuel primary products has probably stagnated or changed only very little from the preceding year.

Preliminary data on merchandise trade by region are provided in Tables II.2 and II.3. The large variations in import volumes by region largely reflect the differences in regional demand and output growth. As can be seen from Table II.2, North America and Asia recorded import growth slightly above 10 per cent or two times faster than the global average. While for North America this was the third year in a row in which import growth exceeded 10 per cent, the developments in Asia illustrate the strength of the region's recovery, which offset the sharp import contraction in the preceding year. While imports of Asia recovered, those of Western Europe recorded a marked deceleration. The transition economies as a group recorded a 10 per cent contraction due to the sharp cut back of imports into Russia and the Ukraine. Imports of Africa and the Middle East changed little in real terms in 1999, also reflecting poor export earnings in recent years.

Table II.2
Growth in the volume of world merchandise trade by selected region, 1997-99
(Percentage change)
    
 Exports Imports
        
 199719981999 199719981999
        
World a10.54.54.5 ………
North America11.03.54.5 13.010.510.5
Latin America11.57.57.0 22.58.5-2.0
Mexico19.511.013.5 28.015.515.0
Other Latin America6.55.52.0 20.04.5-12.0
Western Europe9.55.53.5 9.08.53.5
European Union (15) 9.56.03.5 8.58.54.0
Transition economies10.55.0-3.0 13.55.0-10.0
Asia13.03.56.0 5.5-8.59.0
Japan12.0-1.52.0 1.5-5.59.5
Asia (5) b16.513.011.5 3.0-22.517.5
a Average of export and import growth.
b Indonesia, the Republic of Korea, Malaysia, Philippines and Thailand.
Note: Separate volume data are not available for Africa and the Middle East, although estimates for these regions have been made in order to calculate a world total.

The variation among regional export growth rates in 1999 was smaller than for imports. Despite sharply lower intra-regional trade, Latin America recorded the highest export expansion of all regions. Asian export growth exceeded the global average as Japan's exports recovered and the five Asian developing countries affected most by the 1997/98 financial crisis achieved double-digit export growth. North America's exports accelerated somewhat thanks to the dynamic performance of intra-trade. The deceleration of West European economic activity in 1999 led to markedly lower growth of intra-trade. While intra-European Union exports expanded two times faster than world trade in 1998, its growth in 1999 fell below that of world trade. The transition economies and the Middle East both recorded a contraction of their export volume.


Turning to developments in value terms, the Middle East reports the highest regional export growth rate despite its reduction in export volume. Africa's export growth was, at 8 per cent, the second highest among all regions. This was largely due to the sharp recovery of shipments from the region's oil-exporting countries. However, it should be recalled that for both Africa and the Middle East, the 1999 rise did not fully offset the decrease recorded in the preceding year. Latin America's exports rose by a strong 6 per cent, as the higher growth of Mexico's and some Caribbean countries' exports more than offset the sharp declines reported for all South American countries. A recovery of intra-Asian trade supported by stronger regional growth and appreciating currencies led Asian exports to regain their pre-crisis peak level. North American exports expanded by 4 per cent in 1999, following a small contraction in 1998. The marginal decline in Western Europe's export value was due to a deceleration in volume growth but above all, to a fall of nearly 4 per cent in the region's dollar export prices. The weaker export prices are principally due to the depreciation of the Euro vis-à-vis the US dollar. The sluggishness of Western Europe's import growth, together with the sharp contraction of Russia's imports, contributed to a further decrease in the export value of transition economies in 1999.

Table II.3
Growth in the value of world merchandise trade by region, 1997-99
(Billion dollars and percentage change)
    
 Exports (f.o.b.) Imports (c.i.f.)
        
 Value Annual percentage change Value Annual percentage change
            
 1999 199719981999 1999 199719981999
            
World5460 3.5-1.63.5 5725 3.5-0.84.0
North America934 9.2-0.74.0 1281 10.34.411.5
Latin America292 10.2-1.26.0 329 18.54.8-4.0
Mexico137 15.06.416.5 148 22.613.913.5
Other Latin America156 7.2-6.2-2.0 181 16.4-0.1-14.5
Western Europe2349 -0.63.4-0.5 2417 -0.35.90.5
European Union (15)2176 -0.53.8-0.5 2233 -0.56.31.0
Extra-EU (15) trade799 1.8-0.3-1.5 851 -0.36.22.5
Transition economies212 4.1-4.6-1.5 211 6.5-1.8-13.0
Central/Eastern Europe101 6.39.50.0 129 5.610.8-2.0
Russian Federation74 -0.4-15.90.0 41 6.7-19.8-30.5
Africa113 1.9-15.58.0 132 5.51.20.5
South Africa a27 6.2-9.01.5 27 9.5-9.3-8.5
Major fuel exporters b41 -0.1-31.424.0 30 9.6-0.85.5
Middle East169 4.7-22.422.0 152 8.1-3.24.0
Asia1390 5.4-6.17.5 1201 0.4-17.810.5
Japan419 2.4-7.88.0 311 -3.0-17.211.0
China195 21.00.66.0 166 2.5-1.518.0
Asia (5) c371 5.1-3.59.5 292 -3.1-30.915.5
a Beginning 1998, figures refer to South Africa and no longer to the South African Common Customs Area.
b Angola, Algeria, Congo, Gabon, Libyan Arab Yamahiriya and Nigeria.
c Indonesia, the Republic of Korea, Malaysia, Philippines and Thailand.


3. Commercial services trade

The global export value of commercial services recovered in 1999 after stagnating in 1998. Preliminary data by major services categories indicate that all categories recorded positive growth. Transportation services are estimated to have expanded less than the average growth rate of 1.5 per cent despite the increase in fuel costs. Travel services and the residual grouping of Other business services have both expanded by about 2 to 3 per cent.


The commercial services trade data by region shown in Table II.4 indicate that the most dynamic export and import growth in 1999 was in North America and Asia. While North America's services import growth exceeded its export growth, thereby reducing its traditional surplus in commercial services, Asia's imports and exports expanded at about the same rate (4-5 per cent). The rebound in Asian services trade is much weaker than for Asian merchandise trade, in particular for exports. In contrast to the developments in North America and Asia, Western Europe's services trade expanded less favourably in 1999 than in the preceding year. Available data for the transition economies point to a sharp contraction of both services exports and imports.

Table II.4
Growth in the value of world trade in commercial services by selected region, 1997-99
(Billion dollars and percentage change)
 
 Exports Imports
 
 Value Annual change Value Annual change
 
 1999 199719981999 1999 199719981999
            
World1340 402 1335 313
North America284 825 219 1069
United States252 925 182 11810
Latin America54 79-2 60 134-9
Mexico12 56-3 14 1979
Other Latin America42 810-2 47 124-13
Western Europe630 260 600 071
European Union (15)565 151 555 072
Transition economies47 02-10 44 01-8
Asia267 5-154 337 2-115
Japan60 3-9-3 114 -5-93
Hong Kong, China35 1-103 22 5-2-2
China27 19-2… 32 34-4…
Asia (5) a62 7-233 73 5-255
aIndonesia, the Republic of Korea, Malaysia, Philippines and Thailand
Note: Separate reliable data are not available for Africa and the Middle East, although estimates for these regions have been made to calculate a world total.


4. Trade by region and country

The outstanding high investment and consumption growth in the United States resulted in an expansion of imports of goods and services of more than 10 per cent in both nominal and real terms. Over the last two years United States import demand sustained world trade remarkably. Excluding shipments to the United States, the nominal value of world merchandise and services trade in 1999 would have still been below its 1997 level and the volume expansion of world merchandise trade would have been limited to 6 per cent instead of 9 per cent. The share of the United States in world merchandise imports rose to 18 per cent, the highest US share ever. Strong domestic growth was also one reason why United States merchandise exports in real terms lagged behind global trade growth. All countries having strong trade ties with the United States benefitted from this development, and in particular Canada, which expanded its merchandise exports to the United States over the last two years by about 18 per cent, or twice the rate of global trade growth.

Commercial services' imports of the United States rose by 10 per cent and two times faster than exports. Canada's import growth of commercial services recovered to 5.5 per cent, but remained for the fifth year in a row behind the expansion of its services exports. Although the expansion of United States commercial services' imports has exceeded that of exports since 1997, the United States surplus in services in 1999 still amounted to US$68 billion.

In 1999, Latin America recorded its worst annual economic performance for the last decade, as regional output stagnated and the volume of merchandise imports decreased by 2 per cent. At least eight economies recorded lower output in 1999 than in the preceding year. As in 1998, there is a striking difference in output and trade growth between Mexico and all the other Latin American countries combined. While Mexico's merchandise exports and imports rose over the last two years by more than 20 per cent, other Latin American countries combined reported a fall in exports of nearly 8 per cent and in imports of nearly 15 per cent.

A large part of the divergent performance can be attributed to differences in the export structure. Manufactured goods account for 85 per cent of Mexico's exports, but only 40 per cent for Latin America excluding Mexico. Manufactures enjoyed more stable prices than non-fuel commodities. In addition, Mexico's exports are destined largely to the booming North American market (nearly 90 per cent) while the other Latin American countries ship less than 30 per cent of their exports to North America. Mercosur experienced a contraction of its intra-trade by about one quarter, as output of its member countries declined or stagnated.

For commercial services imports, one can observe a similar divergency, as Mexico's imports rose by 15 per cent, while those of the other Latin American countries contracted by nearly 10 per cent over the last two years. Only for commercial services exports, Mexico reports a stronger decrease than the other Latin American countries in 1999. The somewhat surprising decline reported for Mexico's commercial services exports is attributed to a decrease in revenues from both travel and other business services.

The slowdown in Western Europe's output growth to 2 per cent in 1999 contributed to a markedly lower trade growth in volume terms. As more than two-thirds of Western Europe's trade is intra-regional, weak consumption growth affected both exports and imports. As regards merchandise trade, it is estimated that exports and imports grew in volume terms by about 3.5 per cent and thereby less than world trade. As the Euro and other European currencies weakened vis-à-vis the US dollar, the region's dollar export and import prices decreased on average by about 4 per cent, leading to a stagnation of their trade dollar values in 1999. Austria, France and Sweden were among the West European countries which recorded only moderate import growth, while Norway and Turkey even experienced a contraction of their import volumes in 1999. Spain, Portugal and Ireland, however, continued to be the most dynamic traders in Western Europe, with imports and exports expanding much faster than the European average.

Although output in the transition economies recovered by about 2 per cent, growth remained disappointingly low in the tenth year of transition. Poland is the only country in the region in which the output level in 1999 was above the level attained ten years ago. The sluggishness in Western Europe's economy together with a dramatic shrinkage of Russian imports depressed the region's trade in 1999. Merchandise and commercial services trade were both shrinking in dollar value and volume terms. Most of the decline was concentrated in the CIS member countries. Central and Eastern Europe's merchandise trade slowed down sharply but continued to show positive real growth in 1999. Hungary continued to record the highest trade growth among the Central/East European countries. In 1999, its merchandise exports and imports expanded by about 9 per cent in dollar terms. A major contribution to this strong trade performance was made by the expansion of intra-industry trade in office and telecom equipment and automotive products.

Africa and the Middle East recorded one of their weakest annual GDP growth performances in the 1990s. The rebound in their merchandise exports was largely due to the recovery in oil prices. Africa's merchandise exports rose by 8 per cent in 1999. The major fuel exporters recorded an increase of about one-quarter, which did not fully offset the decline recorded in 1998. South Africa and other non-fuel exporting African countries recorded an increase in their export earnings of less than 2 per cent. African imports stagnated in dollar terms for the second year in a row, as sharp declines in South Africa's imports were offset by increases by African developing countries.

Economic growth patterns differed widely in Asia in 1999. While GDP growth in the two most populous countries in the region, China and India, was about 7 per cent, the output in Japan, the largest economy in Asia, stagnated. Among the five Asian countries severely affected by financial crisis, the Republic of Korea recorded an outstanding recovery with double digit growth, while Indonesian output stagnated. Asian developing countries as a group recorded an output expansion of 6 per cent, at least two times faster than any other developing region.

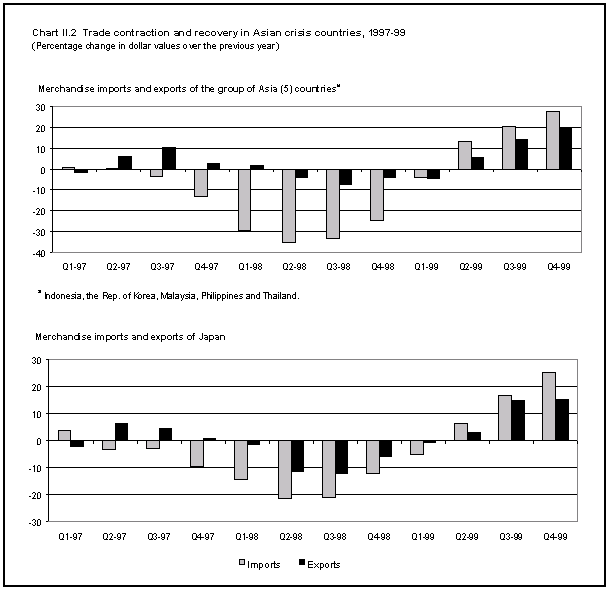
One of the outstanding developments of Asian trade in 1999 was the double digit trade volume growth of the five Asian countries most affected by financial crises in 1997-98. Their export expansion remained very strong (11.5 per cent) and imports rebounded sharply without offsetting fully the contraction of the preceding year. The regional recovery and the cyclical recovery in the electronic goods industry contributed largely to this dynamic growth. For the Republic of Korea and Malaysia, exports of office and telecom equipment accounted for more than 80 per cent of the overall increase of their export value in 1999.

Japan's merchandise trade recovery was strong, taking into account its stagnating economy. However, export and import values did not regain their pre-crisis peak levels. Japan's commercial services exports continued to shrink, while imports picked-up after a marked decrease in 1997-98. China's merchandise imports expanded by 18 per cent while those of Hong Kong, China decreased for the second consecutive year. A notable feature in Asia's trade is the steady decline of the share of Hong Kong, China in Asia's merchandise trade. Hong Kong, China's domestic exports and retained imports had by 1999 fallen below their 1990 level. This decline has to be seen in the context of the relocation of Hong Kong, China's manufacturing industry to China, which in turn has greatly enhanced its share in world exports. In respect to commercial services, however, Hong Kong, China maintains its position as the leading developing country exporter. For the Asian region, exports of commercial services decreased more strongly in 1998 and recovered by far less in 1999 than did merchandise exports. For imports of commercial services, the recovery in 1999 was also far smaller than for merchandise trade.

Looking at trade performance by country, the following features emerge for 1999 trade developments (see Appendix Tables). First, the United States consolidated its leading position in world merchandise imports and world commercial services exports. Its share in world merchandise imports reached, at 18 per cent, its highest level ever. Second, oil-exporting countries recorded in general the highest export growth in 1999 (at least 16 of them recorded export increases ranging from 15 per cent to 50 per cent). For most of them the increase in 1999 did not fully offset the declines recorded in the preceding year. Third, exporters of office and telecom equipment benefitted from the recovery in the global electronic goods industry. The double digit export growth of the Republic of Korea, Malaysia, the Philippines, Costa Rica and Israel was largely due to office and telecom equipment exports. Fourth, a large number (at least 24) of South American and transition economies recorded double-digit decreases in their imports and often also a fall in their export values. The main causes of these bleak developments include the steep fall of intra-regional trade and the low prices of non-fuel commodities. Fifth, the four largest traders in Western Europe (France, Germany, Italy and the United Kingdom) all recorded a small decline in their merchandise export values and minimal changes in their imports.


5. Processing trade contributes to exceptional trade expansion in selected developing countries

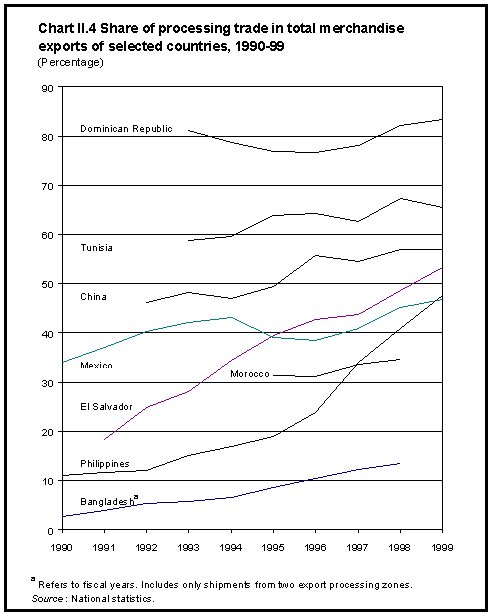
Over the last fifteen years, the outstanding high trade growth recorded by a selected number of developing countries can be partly attributed to the expansion of their "processing trade". Beside multilateral and regional trade liberalization, an increasing number of countries have modified their import regime by granting, under certain conditions, duty-free access to those imports which are bound for the processing and assembling of goods destined for exports. This preferential tariff treatment was initially limited to trade which went through specific areas (e.g. the Special Economic Zones in China or the maquiladoras zones in Mexico) but often extended thereafter to companies located outside these specifically designated areas. While the number of export processing zones has risen to about 850, their success in expanding employment and trade is mixed. In several countries employment in these zones rose sharply and trade was growing rapidly while in many other countries the creation of special zones granting tariff preferences to processing trade had a negligible impact on both trade and employment. In the 1990's the most dynamic processing traders among the developing countries are to be found in Asia and Latin America.

A comprehensive appreciation of the contribution of "processing trade" to the expansion of developing countries' merchandise exports and imports is not attempted here, as the data on processing trade are not as readily available as standard trade statistics. However, the examples given below show that the "processing trade" has gained in importance and often played a crucial part in these countries' overall trade performance. All the eight countries presented in Chart II.4 have recorded an expansion of exports well ahead of the global average in the last decade. Five of them recorded average annual export growth rates around 15 per cent, which is about three times faster than the global trade expansion of 5.5 per cent.

Leading exporters and importers in world merchandise trade (excluding intra-EU trade), 1999


Preferential tariff treatment to "processing trade" is not only a feature of trade regimes in the developing countries. Industrial countries too are often providing duty exemption or reduction on imported goods if these products have been manufactured abroad with materials/components from the importing country. While the value of these imports can be relatively important in bilateral trade flows, their share in total imports is at present rather moderate. For the United States and the European Union the share of imports benefitting from this specific duty exemption amounted to 8 per cent in the US and to 2 per cent in the EU (excluding intra-trade) in 1998. In the United States the share of processing trade in total imports declined markedly as trade with Mexico and Canada became increasingly tariff free with the implementation of NAFTA.

Table II-5
Processing trade and export performance of selected countries, 1990-99
(Billion dollars and percentage)
 Total exportShare ofValue of
 growthprocessing tradeprocessing exports
Country1990-199919981998
 (percent)(percent)(billion $)
 
Dominican Republic an.a. 82.2 4.1 
Tunisia5.9 67.4 4.0 
China13.5 56.9 104.6 
El Salvadorb16.8 48.6 1.2 
Philippines16.5 40.9 12.1 
Mexico14.4 45.2 53.1 
Morocco6.4 34.7 2.6 
Bangladesh c15.2 13.4 0.7 
Memorandum item:      
World total5.4 … … 
 
a Between 1993 and 1998 exports grew by 9.2% and world exports by 7.7% annually.
b Refers to years 1991-1999.
c Refers to fiscal years.
Source: National Statistics


6. Outlook

Global economic output is expected to accelerate from 3 per cent in 1999 to about 3.5 per cent in 2000. The volume of world merchandise trade growth should reach 6.5 per cent. Higher trade growth is possible, in particular, if the demand in Western Europe and Japan pick up more strongly than currently projected.

In 2000, GDP growth of industrial countries could expand by 3 per cent or one half per cent faster than in 1999 as moderately lower growth in the United States is more than offset by higher growth in Western Europe and Japan. Latin America and the Middle East should see a strong pick-up in their GDP growth after experiencing a stagnation of output in 1999. Higher growth is also projected for the transition and African economies. GDP growth of the Asian developing countries is projected to remain unchanged as the impact of the expansionary fiscal policies and the rebuilding of inventories will be less important in 2000 than in 1999, but offset by a strengthening of fixed investment and private consumption.

More robust growth of the world economy in 2000, together with the carry-over effect due to the trade acceleration in the second half of 1999 is projected to lead to export volume growth of at least 6.5 per cent. Most of this higher growth is expected to come from Western Europe and to a lesser extent from Latin America, the Middle East and the transition economies. North America and the developing countries in Asia, which recorded double digit import growth in 1999, are likely to expand their imports less rapidly in 2000, and the projected deceleration of North America's final demand should lead to less dynamic import growth in 2000.

The projections above assume that the oil price will recede from its US$30 per barrel level in the first quarter back to a range of US$20 to US$25 and that major financial market turbulence - in particular a sudden sharp correction of stock markets and the dollar rate - can be avoided in the remaining months of the year. A sharp correction of the stock markets, together with a marked slowing down of United States demand and imports, could alter the trade forecast significantly. Note, for example, that at nearly 350 billion dollars, the United States merchandise trade deficit in 1999 exceeded the total imports of Japan. A disruptive adjustment of the current external imbalances would imply a major risk to trade growth in the near future.


Appendix Table 1
Leading exporters and importers in world merchandise trade, 1999
(Billion dollars and percentage)
 
 Annual Annual
 percentage percentage
ExportersValueSharechange ImportersValueSharechange
 19981999 19981999
 
United States695.012.4-12 United States1059.918.0512
Germany540.59.660 Germany472.68.060
Japan419.47.5-88 United Kingdom320.75.522
France299.05.35-2 Japan310.75.3-1711
United Kingdom268.44.8-3-2 France286.14.97-1
Canada238.44.2011 Canada220.23.737
Italy230.84.11-5 Italy216.03.730
Netherlands204.13.642 Netherlands188.93.251
China194.93.516 Hong Kong, China181.73.1-12-3
Belgium-Luxembourg184.13.363 retained imports a29.20.5-30-20
      Belgium-Luxembourg169.42.972
 
Hong Kong, China174.83.1-70 China165.72.8-118
domestic exports22.20.4-10-10 Mexico148.22.51413
Korea, Rep. of144.22.6-39 Spain145.02.589
Mexico136.72.4616 Korea, Rep. of119.72.0-3528
Taipei, Chinese121.62.2-910 Taipei, Chinese111.01.9-86
Singapore114.62.0-124 Singapore111.01.9-239
domestic exports68.61.2-138 retained imports a65.01.1-3118
Spain109.42.050 Switzerland80.11.450
Malaysia84.51.5-715 Australia69.01.2-27
Sweden84.51.520 Sweden68.21.240
Switzerland80.61.442 Austria67.81.250
Russian Fed. b74.31.3-160      
 
Ireland69.61.2208 Malaysia65.51.1-2612
Austria62.01.17-1 Brazil51.80.9-7-15
Thailand58.41.0-57 Thailand50.60.9-3218
Australia56.11.0-110 Ireland45.60.8142
Saudi Arabia50.50.9-3527 Poland44.80.811-5
Indonesia48.50.9-9-1 India44.60.834
Brazil48.00.9-4-6 Denmark43.30.74-6
Denmark47.80.9-1-1 Russian Fed. b41.10.7-20-30
Norway44.90.8-1813 Turkey39.20.7-5-15
Finland41.50.76-4 Portugal37.60.652
 
Total of above c4927.087.8-- Total of above c4976.084.7--
World c5610.0100.0-23 World c5875.0100.0-14
 
a Retained imports are defined as imports less re-exports.
b Includes trade with the Baltic States and the CIS.
c Includes significant re-exports or imports for re-export.

Appendix Table 2

(Billion dollars and percentage)
 
 Annual Annual
 percentage percentage
ExportersValueSharechange ImportersValueSharechange
 19981999 19981999
 
European Union(15)798.618.90-1 United States1059.923.6512
United States695.016.4-12 European Union (15)851.218.963
Japan419.49.9-88 Japan310.76.9-1711
Canada238.45.6011 Canada220.24.937
China194.94.616 Hong Kong, China181.74.0-12-3
Hong Kong, China174.84.1-70 retained imports a29.20.6-30-20
domestic exports22.20.5-10-10 China165.73.7-118
Korea, Rep. of144.23.4-39 Mexico148.23.31413
Mexico136.73.2616 Korea, Rep. of119.72.7-3528
Taipei, Chinese121.62.9-910 Taipei, Chinese111.02.5-86
Singapore114.62.7-124 Singapore111.02.5-239
domestic exports68.61.6-138 retained imports a65.01.4-3118
 
Malaysia84.52.0-715 Switzerland80.11.850
Switzerland80.61.942 Australia69.01.5-27
Russian Fed. b74.31.8-160 Malaysia65.51.5-3512
Thailand58.41.4-57 Brazil51.81.2-7-15
Australia56.11.3-110 Thailand50.61.1-3218
Saudi Arabia50.51.2-3527 Poland44.81.011-5
Indonesia48.51.1-9-1 India44.61.034
Brazil48.01.1-4-6 Russian Fed. b41.10.9-20-30
Norway44.91.1-1813 Turkey39.20.9-5-15
India36.50.9-49 Norway33.80.81-7
 
Philippines35.00.81819 Israel33.20.7-513
United Arab Emirates29.50.7-1315 Philippines32.60.7-184
Czech Rep.26.80.6162 Saudi Arabia30.00.740
Poland26.80.610-5 United Arab Emirates28.90.6-96
South Africa c26.70.6-91 Czech Rep. d28.90.660
Turkey26.20.63-3 Hungary27.70.6218
Israel25.30.6210 South Africa c26.80.6-9-8
Hungary24.60.6207 Argentina25.50.63-19
Argentina23.30.60-12 Indonesia23.90.5-34-13
Venezuela18.90.4-2110 Egypt16.20.4220
 
Total of above e3884.091.8- - Total of above e4073.090.7--
World (excl. intra-EU trade) e4232.0100.0-44 World (excl. intra-EU trade) e4494.0100.0-35
 
a Retained imports are defined as imports less re-exports.
b Includes trade with the Baltic States and the CIS.
c Beginning 1998, figures refer to South Africa and no longer to the South African Common Customs Area.
d Imports are valued f.o.b.
e Includes significant re-exports or imports for re-export.

Appendix Table 3
Leading exporters and importers in world trade in commercial services, 1999
(Billion dollars and percentage)
         
   Annual    Annual
   percentage    percentage
ExportersValueSharechange ImportersValueSharechange
   19981999    19981999
           
United States251.718.825 United States182.313.7810
United Kingdom101.47.672 Germany127.29.532
France79.35.95-6 Japan113.98.5-93
Germany76.85.73-3 United Kingdom81.46.1114
Italy64.54.80-3 Italy62.74.770
Japan59.84.5-9-3 France59.24.45-9
Spain54.14.01211 Netherlands46.53.540
Netherlands53.14.033 Canada37.12.8-45
Belgium-Luxembourg37.62.864 Belgium-Luxembourg35.52.684
Hong Kong, China35.42.6-103 China32.12.4-4…
           
Austria32.62.493 Spain30.92.31312
Canada32.42.427 Austria29.52.26-2
Switzerland27.22.055 Korea, Rep. of26.72.0-1914
China26.62.0-2… Ireland23.51.83218
Korea, Rep. of25.01.9-65 Taipei, Chinese23.21.7-40
Singapore22.91.7-4025 Sweden22.81.7115
Sweden18.01.312 Hong Kong, China22.41.7-2-2
Australia17.21.3-139 Singapore19.31.4-78
Denmark16.01.268 Australia18.01.3-86
Turkey16.01.221-31 India17.31.31622
           
Taipei, Chinese14.81.1-2-11 Denmark16.21.2135
Thailand14.11.1-168 Switzerland15.71.283
Norway13.71.0-3-2 Norway15.41.242
India13.21.02419 Thailand13.91.0-3117
Mexico11.60.96-3 Mexico13.71.079
Malaysia10.80.8-24… Malaysia13.01.0-24…
Greece10.50.86… Indonesia12.70.9-288
Israel10.30.8814 Russian Fed.11.70.9-14-27
Poland9.80.721-10 Brazil11.60.99-26
Russian Fed.9.70.7-9-25 Israel10.70.8512
           
Total of above1165.087.1-- Total of above1145.085.9--
World1340.0100.00.01.5 World1335.0100.00.52.5

›››Archivio
DALLA PRIMA PAGINA
Stretto del Bosforo, i transiti di navi crollano del -23,2%
Ankara
Nel terzo trimestre dimezzati i passaggi delle portarinfuse. Più contenuta la flessione nei Dardanelli (-12,8%), mentre tengono le portacontainer
Nel terzo trimestre i terminal di Eurokai hanno movimentato un traffico record di 3,9 milioni di container (+9,4%)
Amburgo
Nei primi nove mesi del 2026 il totale è stato di oltre 11,3 milioni di teu (+8,7%)
ETS marittimo, per Bruxelles il sistema funziona. I porti temono la fuga dei traffici
Bruxelles
L'ultimo rapporto della Commissione sul 2025 segnala emissioni in calo del 4% e conformità oltre il 99%. Sul rischio di elusione, però, non porta dati nuovi
Nel terzo trimestre i ricavi della Yang Ming sono cresciuti del +52,4%
Keelung
Attesa nell'ultima parte del 2026 una prosecuzione delle condizioni favorevoli allo shipping
USA-Cina, la distensione commerciale coinvolge anche porti e cantieri navali
Pechino
Pechino proroga la sospensione degli oneri portuali sulle navi statunitensi e delle indagini sulle ripercussioni delle misure americane sulla propria industria marittima
Alfa Laval acquisisce Navtor per 700 milioni di dollari
Lund/Egersund
La società norvegese di soluzioni digitali per la navigazione sarà integrata nella divisione Ocean del gruppo svedese
Boluda Towage compra la società olandese di rimorchio Muller Dordrecht
Dordrecht/Valencia
Ha una flotta formata da 16 rimorchiatori e otto chiatte
Lo scorso mese i transiti navali nel canale di Suez sono aumentati del +32,1%
Il Cairo
Crescita del +86,8% del tonnellaggio e del +94,1% dei diritti di transito
Ferrovia, spazi e ambiente tra le priorità emerse dagli incontri sul nuovo PRP dei porti di Genova e Savona-Vado
Genova
Conclusa la prima fase di ascolto dell'AdSP con 65 audizioni e oltre 120 soggetti coinvolti
Fincantieri sigla accordi con J.A. Solutions, Navantia e Naval Group
Parigi
Intensa con l'azienda danese nel campo dei sistemi modulari e containerizzati avanzati per unità navali riconfigurabili
Meno container, più incassi: la divisione marittima della Maersk cresce con i noli
Copenaghen
Nel terzo trimestre i volumi sono calati del -0,8%, ma tariffe e congestione hanno elevato l'EBIT di Ocean a 2,6 miliardi
Dall'Egitto al Marocco, passando per Gioia Tauro: l'ETS sposta i container verso i porti extra-UE?
Bruxelles
Uno studio promosso da Assarmatori vede segnali di trasferimento già in atto e chiede correttivi
Nel terzo trimestre le navi della ONE hanno trasportato volumi record di container
Singapore
I ricavi sono aumentati del +36,5%. Performance trainate dalla domanda di spedizioni transpacifiche
Wallenius Wilhelmsen archivia un terzo trimestre con ricavi record che, però, crescono meno dei costi
Lysaker
Lieve calo dei volumi di veicoli trasportati dalla flotta
Canale di Suez, segnali di ripresa dei transiti navali a settembre
Ismailia
Persistono tuttavia i contraccolpi della crisi nel Mar Rosso
Taranto, la crisi siderurgica continua a pesare sul porto
Taranto
Le rinfuse liquide sostengono i volumi, ma nei primi nove mesi del 2026 il traffico complessivo cala del 5,7%. Ancora volatile la movimentazione dei container
Dazi portuali USA sulle navi cinesi, la coalizione del commercio chiede la sospensione permanente
Washington
Centinaia di associazioni scrivono a Greer in vista della scadenza del 9 gennaio 2027. Tra loro il World Shipping Council
T&E, l'ETS diventi il motore degli investimenti per gli e-fuel di aerei e navi
Bruxelles
Le richieste dell'organizzazione per la revisione del sistema di scambio di quote: più risorse europee, un fondo dedicato e aste a doppio lato
Nella prima metà del 2026 il traffico delle merci nel porto di Livorno è calato del -3,6%
Livorno
Flessione anche per i porti elbani (-3,3%). In controtendenza il porto di Piombino con un +5,7%
Merci in discesa nei porti dell'Adriatico meridionale nei primi sei mesi del 2026
Bari
Il sistema perde 676mila tonnellate rispetto al 2025, quasi tutte tra i due scali maggiori
Nel terzo trimestre il traffico navale nel canale di Panama è risultato stabile
Panamá/Balboa
In crescita, tuttavia, il tonnellaggio delle navi e il volume di merci transitate
Le Aziende informano
Ufficiali di Macchina: l'Accademia Italiana della Marina Mercantile apre le selezioni per il corso ITS triennale gratuito. Scadenza 26 ottobre
ETS marittimo, FEPORT sostiene la misura anti-elusione legata ai carichi
Bruxelles
È la soluzione più efficace - sostiene la federazione dei terminalisti europei - per proteggere la competitività dei porti dell'UE
COSCO Shipping, ricavi +29% e utile +82%: il merito è dei noli, più che dei volumi
Hong Kong
Il mercato transpacifico è il motore dei conti del gruppo cinese
Norwegian Cruise Line Holdings, utile netto in crescita ma margini in calo nel terzo trimestre
Miami
Ad APM Terminals l'ulteriore fase di ampliamento del porto marocchino di Tanger Med
Rabat
Previsto un investimento di oltre 800 milioni di dollari per realizzare 1,2 chilometri di banchine
Porto di Barcellona, al via il progetto per la riduzione, da sette a cinque, dei terminal crociere
Barcellona
Revisione della concessione detenuta da Creuers del Port de Barcelona
Boluda-Samskip, nuova aggregazione nello short sea shipping europeo
Valencia/Rotterdam
Il gruppo spagnolo ha firmato un accordo per rilevare tutte le attività del gruppo olandese e ampliare la propria piattaforma multimodale
Cantieri indiani nella lista UE del riciclaggio navale, ECSA chiede il sì agli eurodeputati
Bruxelles
Esortazione a respingere un mozione che si oppone alla proposta della Commissione
CVC DIF ha acquisito una quota di maggioranza del cantiere navale spagnolo Cernaval
Schiphol
La società iberica dà lavoro a circa 275 persone
Contship Italia acquisisce il gruppo Tarros
Melzo/La Spezia
Passano di mano tutte le attività e gli asset che costituiscono il sistema integrato di servizi del gruppo spezzino
Sospesa la crociera residenziale della statunitense Villa Vie Residences
Fort Lauderdale/Sihanoukville
La compagnia attribuisce il fermo della nave al rialzo dei costi del fuel e lavora ad un piano di ristrutturazione e ricapitalizzazione
Wallenius Wilhelmsen ordina quattro PCTC da 9.900 ceu più otto in opzione
Lysaker
Accordo con il cantiere navale cinese Jinling Shipyard (Jiangsu)
Royal Caribbean, trimestre record: ricavi a 5,59 miliardi. Rialzo delle previsioni per l'intero 2026
Miami
EBITDA a 2,53 miliardi e passeggeri a 2,68 milioni nel periodo luglio-settembre
Sicurezza in mare, ETS, bandiera e lavoro al centro della relazione del presidente di Confitarma
Roma
Zanetti chiede un'alleanza europea per la libertà di navigazione, un patto nazionale per la transizione e meno burocrazia per la bandiera italiana
Global Ports Holding sigla il contratto di concessione per il porto crociere di Saint Vincent
Istanbul
L'accordo ha una durata di 30 anni
La famiglia Sunde vende Color Line a Stena
Göteborg
Il gruppo svedese dei traghetti rileva la maggiore compagnia norvegese di cruise ferry
Porti cinesi, la corsa rallenta
Pechino
Dopo 25 anni di crescita il traffico di merci è quasi fermo, ma i container battono ancora record
Lorenzo Sanna è il nuovo presidente dell'ANPAN
Sestri Levante
Parmigiani: sul Protocollo Alto Mare si torni alla dichiarazione cartacea del comandante
Il 2027 sarà nuovamente un anno record per la crocieristica italiana
Livorno
Previsti circa 16 milioni di passeggeri, con una crescita del +4%
Riforma dei porti, in Commissione solo accantonamenti e respingimenti
Roma
Alla Camera nessun emendamento approvato in tre settimane. Unica apertura: il personale delle Autorità di Sistema Portuale
Autotrasporto, tregua vicina. Il governo sblocca fondi per il gasolio e riforme strutturali
Roma
Varato il decreto d'urgenza con crediti d'imposta, stop ai leasing e tutele sul fuel surcharge
La flotta di portacontainer e car carrier dual-fuel supera le 500 unità
Washington
Balzo del +41% rispetto a settembre 2025. Gli investimenti dell'industria hanno oltrepassato i 200 miliardi di dollari
Corridoi marittimi verdi, la Cina guida la corsa
Shanghai
Quasi un quinto delle iniziative mondiali coinvolge un porto cinese. Il rapporto del Global Maritime Forum indica come punti di forza carburanti e collaborazione, mentre la domanda resta debole
Nel terzo trimestre il traffico delle merci nei porti spagnoli è cresciuto del +2,1%
Madrid
Trainano le rinfuse. Stabili i carichi containerizzati
L'UE investe nella rivoluzione verde dei mari
Bruxelles
Dall'ammoniaca all'e-metanolo, dai traghetti elettrici alla cattura della CO2: finanziati i progetti che ridisegnano il futuro dello shipping europeo
Autotrasporto, le associazioni chiedono lo stop ai blocchi nel Sud
Roma/Modena
Dopo l'incontro con Salvini, le sigle di categoria sollecitano l'intervento di Piantedosi. Ruote Libere replica: ascoltare chi protesta, non reprimere
Intesa APM Terminals-Hateco per sviluppare una rete di terminal ferroviari merci nel Vietnam settentrionale
Copenaghen
Stimato un investimento iniziale di circa 3,5 miliardi di dollari
IFM Investors rileverà le quote di CPPIB e OMERS in Associated British Ports
Londra
Raggiunta un'intesa per il passaggio di mano del 63,9% del capitale del gruppo portuale britannico
DSV, nel terzo trimestre Air & Sea e Contract Logistics trainano, mentre il trasporto stradale frena
Copenaghen
La divisione stradale paga i problemi seguiti all'integrazione di Schenker
Decarbonizzazione dello shipping, il Regno Unito impari dagli errori del FuelEU Maritime
Londra
La UK Chamber of Shipping presenta al governo un documento con le lezioni dei primi due anni di applicazione del regolamento europeo
Il porto di Anversa-Bruges torna a crescere nel terzo trimestre, con un +2,5% dopo due trimestri in calo
Anversa
Container, ro-ro e rinfuse secche trainano la ripresa, mentre acciaio e prodotti energetici restano in difficoltà
Interferry rinnova l'allarme per il rinvio dell'inclusione dell'autotrasporto nell'EU ETS
Victoria
Roos: gli oneri e le sfide della decarbonizzazione non possono essere sopportati da singoli settori
Il porto di Trieste recupera sui container nel terzo trimestre, ma la ferrovia resta in affanno
Trieste
Rinfuse liquide in ripresa
Traffico trimestrale delle crociere record nei terminal di Global Ports Holding
Istanbul
In calo solo i numeri della regione del Mediterraneo orientale e dell'Adriatico
Rheinmetall conferma la partnership con MSC per l'acquisizione del cantiere navale rumeno di Mangalia
Düsseldorf
Il prezzo d'acquisto di circa 138 milioni di euro sarà corrisposto congiuntamente dai due partner
Stretto di Hormuz, ancora un weekend di attacchi alle navi
Teheran/Southampton
Utilizzato per la prima volta un razzo anticarro RPG sparato da una piccola imbarcazione
Porto di Rotterdam, nel terzo trimestre calo delle merci varie e aumento delle rinfuse
Rotterdam
Nei primi nove mesi del 2026 sono state movimentate 323,2 milioni di tonnellate (+0,9%)
Nasce l'Osservatorio della cantieristica ligure: un settore da due miliardi di euro e oltre 10mila occupati
Genova
AdSP, Confindustria Genova e Unione Industriali Savona avviano il monitoraggio permanente del comparto
Per la BPA la crescita dei container britannici dipende dagli investimenti, non dal carbon leakage
Londra
Un rapporto dell'associazione britannica contesta l'Osservatorio spagnolo: l'indicatore in teu-miglia non misura i volumi reali e amplifica l'effetto dell'ordine degli scali
ETS, lo shipping pesa per il 10% delle emissioni ma paga quasi il 20% del conto
Bruxelles
Studio ECSA: gli armatori europei chiedono di triplicare le quote destinate al meccanismo SMAP per i carburanti e le tecnologie sostenibili
A.P. Moller Capital acquisirà il gruppo portuale Portek International
Copenaghen
Verrà ceduto dalla giapponese Mitsui & Co.
Washington-Madrid, lo scontro sui porti rischia di diventare una guerra commerciale
Washington
La FMC propone un prelievo di 200mila dollari per viaggio sulle navi sotto bandiera spagnola e limitazioni all'import di alcuni prodotti
Ansis Zeltins è stato rieletto presidente dell'European Sea Ports Organisation
Bruxelles
L'Associazione dei Porti Islandesi ha aderito ad ESPO
Quest'anno Blu Navy ha registrato una crescita del +12% dei passeggeri trasportati
Portoferraio
Aumentati anche i veicoli trasportati (+11%)
Uiltrasporti, bene l'impegno del PD su emendamenti per lavoro portuale e marittimo
Roma
È l'unica forza politica - sottolinea il sindacato - che ha risposto finora alle nostre richieste d'incontro
Il 17 novembre a Ravenna un convegno su presente e futuro delle Autostrade del Mare in Italia
Ravenna
Nel 1991 prendeva il via la linea marittima Ravenna-Catania
Nei primi nove mesi del 2026 il traffico dei container nel porto di Gioia Tauro è cresciuto del +1,7%
Roma
Aggiornamento congiunturale della Banca d'Italia sull'economia della Calabria
FS Engineering e Sogesid, accordo per lo sviluppo di progetti infrastrutturali in Italia e all'estero
Roma
Focus nazionale sull'infrastrutturazione portuale, sui sistemi logistici e sulle infrastrutture connesse alla mobilità
Tariffe dei centri di addestramento marittimo, il TAR Lazio ha sospeso gli aumenti
Roma
Accolta la richiesta cautelare di CONFORMAR e ANIFORMAR. Udienza di merito il prossimo 16 marzo
Global Ship Lease, ricavi in crescita del +4,5% nel terzo trimestre 2026
Atene
Nuova linea di credito da un miliardo di dollari per finanziare 15 nuove portacontainer
Il Corso Papagno di Assagenti ha formato oltre mille giovani agenti e raccomandatari marittimi
Genova
Dal 2017 è fornito a livello nazionale
AIRIDEA, nuovo collegamento aereo Genova-Marsiglia con il supporto di Genova Industrie Navali
Genova
Servizio pensato per agevolare gli spostamenti di lavoro tra le due città
Joint venture di Fincantieri e Republikorp per rafforzare la cantieristica navale in Indonesia
Parigi
Costituito oggi a Cagliari il Propeller Club Port of Sardinia
Genova
È il 27° Club dell'associazione nazionale che comprende oltre 1.600 soci
L'indiana Adani Ports compra la società terminalista olandese Evos
Ahmedabad/Amsterdam
Transazione del valore di 2,56 miliardi di euro
Hapag-Lloyd ha perfezionato l'acquisizione del 25% in APM Terminals Maasvlakte II
Amburgo
Rinnovato il consiglio direttivo di Interferry
Victoria
Le nomine in occasione conferenza per il 50° anniversario dell'associazione a Bangkok
DIS, utile in crescita nel terzo trimestre 2026
Lussemburgo
Dopo il boom del secondo trimestre, la redditività resta su livelli elevati
Arsenio Dominguez continuerà a guidare l'IMO sino a fine 2031
Londra
Lo ha deciso il Consiglio. La nomina dovrà essere ratificata dall'assemblea
DHL cresce nel terzo trimestre, Express e Forwarding trainano ricavi e utili
Bonn
Fatturato a 22,7 miliardi di euro (+12,6%) e EBIT a 1,7 miliardi (+16,2%)
Il Tribunale UE ha annullato la revoca del riconoscimento al registro navale russo
Lussemburgo
Restano in vigore il divieto di investimenti e il divieto di transazioni
Il bioGNL italiano cerca spazio tra ETS, FuelEU e incentivi nazionali
Rimini
Assogasliquidi chiede procedure di certificazione più semplici e misure per rendere competitiva la produzione nazionale
Accordo Fincantieri - Leonardo per rafforzare il ruolo di Orizzonte Sistemi Navali
Trieste/Roma
Le aziende puntano al consolidamento del ruolo industriale e commerciale della joint venture
Porto di Fiume, le merci varie spingono Luka Rijeka, mentre il container terminal Adriatic Gate perde terreno
Rijeka
Nei primi nove mesi del 2026 il traffico complessivo cala del -15% a 3,83 milioni di tonnellate
Confetra, il governo vuole abolire la tassa sui piccoli pacchi
Roma
Soddisfazione per la scelta del governo nel disegno di legge di bilancio
A Taranto è stata istituita una Comunità Energetica Rinnovabile Portuale
Taranto
Tra gli obiettivi, lo sviluppo del porto pugliese quale polo energetico
Filt e Uilt, il sistema del lavoro portuale temporaneo non è anacronistico
Roma
Definirlo così - denunciano i sindacati - significa travisare la natura e il ruolo dell'art. 17 della legge 84/94
Nuovo record trimestrale di traffico delle merci nei porti albanesi
Tirana
Nel periodo luglio-settembre i passeggeri sono diminuiti del -5,4%
Conti in salita per FedEx, ma l'utile netto scende del -68%
Memphis
Pesa la minusvalenza non monetaria legata allo spin-off di FedEx Freight
Nel terzo trimestre Kalmar ha registrato una crescita del +22% dei nuovi ordini
Helsinki
Stabile il fatturato. Utile netto in calo del -14%
Nel terzo trimestre le vendite di container prodotti dalla CIMC sono aumentate del +30%
Hong Kong
Attività commerciale trainata dai dry box (+36%). Calo del -28% dei reefer
Porti, nuovi investimenti in Toscana e Sardegna
Livorno/Cagliari
Approvati i bilanci previsionali 2027 delle due AdSP. In primo piano la banchina di Piombino, le opere a Livorno e i dragaggi e gli interventi di elettrificazione negli scali sardi
Porti italiani, trovare personale qualificato è sempre più difficile
Napoli
Un'analisi di Randstad Research su 13 profili professionali evidenzia anche un marcato squilibrio di genere
COSCO Shipping Ports registra ricavi record per il terzo trimestre
Hong Kong
Nel periodo luglio-settembre l'utile netto è stato di 102,5 milioni di dollari (+3,4%)
Ok al bilancio di previsione 2027 e al POT 2027-2029 dell'AdSP dei Mari Tirreno Meridionale e Ionio
Gioia Tauro
Il documento previsionale presenta entrate per circa 24 milioni di euro e spese per circa 88 milioni
Il ravennate Bongiovanni confermato presidente dei Giovani di Federagenti
Roma
Rinnovo del consiglio direttivo della federazione
Approvato il Piano Operativo Triennale 2027-2029 del sistema portuale dell'Adriatico Centrale
Ancona
Previsti 308 milioni di euro di investimenti, di cui 218 milioni per le Marche e 91 milioni per l'Abruzzo
Approvato il bilancio di previsione 2027 dell'AdSP della Liguria Occidentale
Genova
Rinviata al 2028 la nuova sovrattassa sulle merci
DP World inaugura un magazzino a temperatura controllata nei pressi di Bologna
Bologna
Struttura della superficie di 22mila metri quadri
Saipem si aggiudica due nuovi contratti di perforazione offshore
Milano
Il valore complessivo delle commesse è di circa 121 milioni di dollari
Hanwha porta il cantiere navale di Filadelfia sotto il controllo della divisione difesa
Arlington
L'obiettivo è di integrare la costruzione di navi commerciali e militari
Porti di Spezia e Carrara, ok al Programma Triennale dei Lavori Pubblici 2027-2029 e al Bilancio di Previsione 2027
La Spezia
Pisano: PTLP concreto e coerente con le risorse attualmente disponibili
Concessioni portuali, nuovo stop del TAR all'aumento dei canoni 2025
Roma
Accolto il ricorso di Assiterminal e di sedici società portuali
Incremento degli ordini trimestrali a Wärtsilä, ma non nel segmento Marine
Helsinki
Nel periodo luglio-settembre l'azienda ha registrato un utile netto di 125 milioni di euro (-31%)
Montaresi nominata segretario generale dell'AdSP del Mar Ligure Orientale per altri quattro anni
La Spezia
Rinnovo della carica su proposta del presidente Pisano
Doppia cerimonia per due navi di Explora Journeys nel cantiere genovese della Fincantieri
Genova
Varo di “Explora V” e cerimonia della moneta di “Explora VI”
L'italiana CMD passa sotto il controllo del gruppo emiratense EDGE
Abu Dhabi/Roma
I cugini Mariano e Giorgio Negri mantengono una significativa quota di partecipazione
L'AdSP del Tirreno Settentrionale presenta il nuovo layout del porto di Piombino
Livorno
Gariglio: un passo concreto per la riconversione industriale e per il futuro di Piombino
FS Logistix ha acquistato sei nuove locomotive della CZ LOKO per i servizi merci e le manovre
Roma/Praga
È il quarto ordine di questa tipologia all'azienda ceca in dieci anni
Porto di Bremerhaven, la nave da crociera Mein Schiff 3 ha urtato due portacontainer
Brema
Nessun ferito. Cancellata la crociera
Paolo Moretti è stato nominato amministratore delegato di RINA Spa
Genova
Giosuè Vezzuto ha assunto il ruolo di amministratore delegato di RINA Services
Joint venture di HD Hyundai e Kiewit per insediare un nuovo cantiere navale negli USA
Houston/Seul
Prevista la costruzione sia di navi militari che commerciali
Calo degli ordini trimestrali di mezzi portuali della Konecranes mentre aumenta il fatturato
Helsinki
Assai positivo il terzo trimestre di Kuehne+Nagel
Schindellegi
Crescita dei risultati economici e operativi in tutti i segmenti d'attività
La corsa di Wildcat alla difesa USA: accordo in esclusiva per lo storico cantiere navale Fraser
Superior
L'operazione del fondo di Miami Beach si pone nel quadro del piano governativo per il rilancio della cantieristica americana
Porto di Ancona, rilascio della prima autorizzazione unica ZES
Ancona
Sbloccato giorni un investimento di tre milioni di euro per la cantieristica degli yacht
Autorizzato l'accesso al porto di Ravenna a navi con pescaggio massimo di 11,00 metri
Ravenna
Benevolo: è una tappa fondamentale per lo sviluppo economico e strategico dello scalo
Porto di Genova, estesa l'autorizzazione per i controlli alimentari al terminal PSA SECH
Genova
Il provvedimento del Ministero della Salute amplia le categorie di prodotti sottoponibili a controllo
PROSSIME PARTENZE
Visual Sailing List
Porto di partenza
Porto di destinazione:
- per ordine alfabetico
- per nazione
- per zona geografica
Giovedì alla Camera l'Unione Interporti Riuniti presenterà il progetto ELODIE
Roma
Lo scopo è di realizzare una federazione digitale degli interporti
ABB, ordini record a 12 miliardi di dollari nel terzo trimestre
Zurigo
In aumento anche ricavi e utili, mentre il gruppo annuncia una joint venture con Mitsubishi Electric
Nel terzo trimestre del 2026 i container nel porto di Barcellona sono diminuiti del -9,2%
Barcellona
Il calo è stato determinato dalla riduzione del -19,9% del traffico di transhipment
Nuovo record di traffico trimestrale dei container per i terminal di COSCO Shipping Ports
Hong Kong
Nel periodo luglio-settembre In anche dei volumi movimentati da CMPort
Ad agosto i porti della Liguria Occidentale hanno movimentato 5,2 milioni di tonnellate di merci (+1,6)
Genova
A Genova è stato registrato un aumento del +6,1%, mentre Savona-Vado Ligure ha accusato un calo del -10,0%
Raben Italy inaugura un nuovo magazzino a Pomezia
Milano
L'obiettivo è consolidare il posizionamento e l'espansione territoriale nei trasporti su gomma
Porto della Spezia, accordo per sviluppare progetti sulla blue economy e sulla sicurezza
La Spezia
È stato siglato dall'AdSP e dalla Fondazione del Polo Nazionale della Dimensione Subacquea
Il porto di Long Beach festeggia il nuovo record di traffico mensile dei container
Long Beach
Nuovo massimo storico anche nel trimestre luglio-settembre
Avviata la gara per la demolizione parziale del molo Nord del porto di Ancona
Ancona
L'intervento include la regolarizzazione dei relativi fondali
HMM investe oltre 1,6 miliardi di dollari per 12 nuove portacontainer
Busan
Entro il 2029 la presa in consegna di otto navi da 13.000 teu, tre da 2.800 teu ed una da 1.700 teu
Paolo Pessina confermato alla presidenza di Federagenti
Roma
Voto unanime dell'assemblea della Federazione
Avviata la trattativa per il rinnovo del Ccnl unico dell'industria armatoriale
Roma
Le parti hanno concordato un fitto calendario di incontri
Nel terzo trimestre il traffico dei container nel porto di Hong Kong è cresciuto del +15,1%
Hong Kong
A settembre l'aumento è stato del +25,0%
Formazione marittima, ricorso al TAR contro l'aumento delle tariffe delle Capitanerie di Porto
Roma
ANIFORMAR, CONFORMAR e 15 centri di addestramento contestano il decreto MIT-MEF: gli incrementi arrivano fino al 149,3%
Il gruppo Spinelli ha attivato un nuovo deposito per i container vuoti a Novi Ligure
Genova
Investimento del valore di 14 milioni di euro
Rhenus integra i propri servizi logistici in un unico hub all'Interporto di Padova
Padova
Nel sito confluiranno trasporto su strada, spedizioni aeree e marittime, warehousing e servizi specializzati
Muore un camionista al porto canale di Cagliari
Cagliari
Sarebbe stato schiacciato da un carico di grandi tubi
Lavoro marittimo, preoccupazione di Confitarma per l'incertezza derivante dalla posizione interpretativa dell'Agenzia delle Entrate
Piano di Mitsubishi Heavy Industries per ampliare la propria capacità nella cantieristica navale
Tokyo
L'azienda prevede investimenti pari a 100 miliardi di yen
Trasportounito, folle il governo se pensa che la crisi dell'autotrasporto si possa risolvere da sola
Roma
Sollecitata l'applicazione della clausola di adeguamento del costo del gasolio
Emanuele Grimaldi è il nuovo presidente della Malta International Shipowners Association
La Valletta
Subentra a Marily Frangista, alla guida dell'associazione dall'aprile 2022
Al via domattina a Padova la quarta edizione di Green Logitics Expo
Padova
Vedrà la partecipazione di oltre 300 espositori e lo svolgimento di 30 eventi convegnistici
Nel terzo trimestre di quest'anno il traffico delle merci nei porti turchi è diminuito del -1,1%
Ankara
I volumi da e per l'Italia è cresciuto del +6,2%
Assiterminal, la flessibilità dei PRP tenga conto del mercato rilevante in cui operano i porti
Genova
Cetus Maritime progetta di quotarsi sul mercato azionario Euronext Growth Oslo
Hong Kong
Acquisizione di 16 navi in vista dell'ingresso in Borsa
Sabato un jet statunitense ha colpito una rinfusiera nel Golfo di Oman
Tampa
Centcom: la nave aveva tentato di forza il blocco navale contro l'Iran
PORTI
Porti italiani:
Ancona Genova Ravenna
Augusta Gioia Tauro Salerno
Bari La Spezia Savona
Brindisi Livorno Taranto
Cagliari Napoli Trapani
Carrara Palermo Trieste
Civitavecchia Piombino Venezia
Interporti italiani: elenco Porti del mondo: mappa
BANCA DATI
ArmatoriRiparatori e costruttori navali
SpedizionieriProvveditori e appaltatori navali
Agenzie marittimeAutotrasportatori
MEETINGS
Il 17 novembre a Ravenna un convegno su presente e futuro delle Autostrade del Mare in Italia
Ravenna
Nel 1991 prendeva il via la linea marittima Ravenna-Catania
Evento di Assologistica per discutere della strategia mediterranea per la competitività italiana
Roma
Si terrà il prossimo 30 ottobre a Napoli
››› Archivio
RASSEGNA STAMPA
Cosco Shipping arm readies China IPO to capitalise on global shipbuilding wave
(South China Morning Post)
Rosatom expects cargo traffic along Northern Sea Route to rise 14% in 2026 - CEO
(Interfax)
››› Archivio
FORUM dello Shipping
e della Logistica
Relazione del Presidente Mario Zanetti
Roma, 27 ottobre 2026
››› Archivio
Colpita una nave in prossimità dello Stretto di Hormuz
Southampton
Un proiettile ha provocato un incendio successivamente domato
OOCL, crescita del +9,0% dei volumi trasportati dalle navi nel terzo trimestre
Hong Kong
Il rialzo del valore dei noli marittimi fa segnare un +45,1% ai ricavi
HD Hyundai Marine Solution comprerà l'americana Goltens Worldwide
Dubai/Seongnam
L'azienda si occupa di riparazione e manutenzione di motori navali di grandi dimensioni e macchinari industriali
UNATRAS al governo: sbloccare subito le misure sul caro-gasolio
Roma
Le associazioni dell'autotrasporto denunciano ritardi e incertezze sull'attuazione dell'intesa del 22 maggio e chiedono una convocazione urgente
- Via Raffaele Paolucci 17r/19r - 16129 Genova - ITALIA
tel.: 010.2462122, fax: 010.2516768, e-mail
Partita iva: 03532950106
Registrazione Stampa 33/96 Tribunale di Genova
Direttore responsabile Bruno Bellio
Vietata la riproduzione, anche parziale, senza l'esplicito consenso dell'editore
Cerca su inforMARE Presentazione
Feed RSS Spazi pubblicitari

inforMARE in Pdf Archivio storico
Mobile